


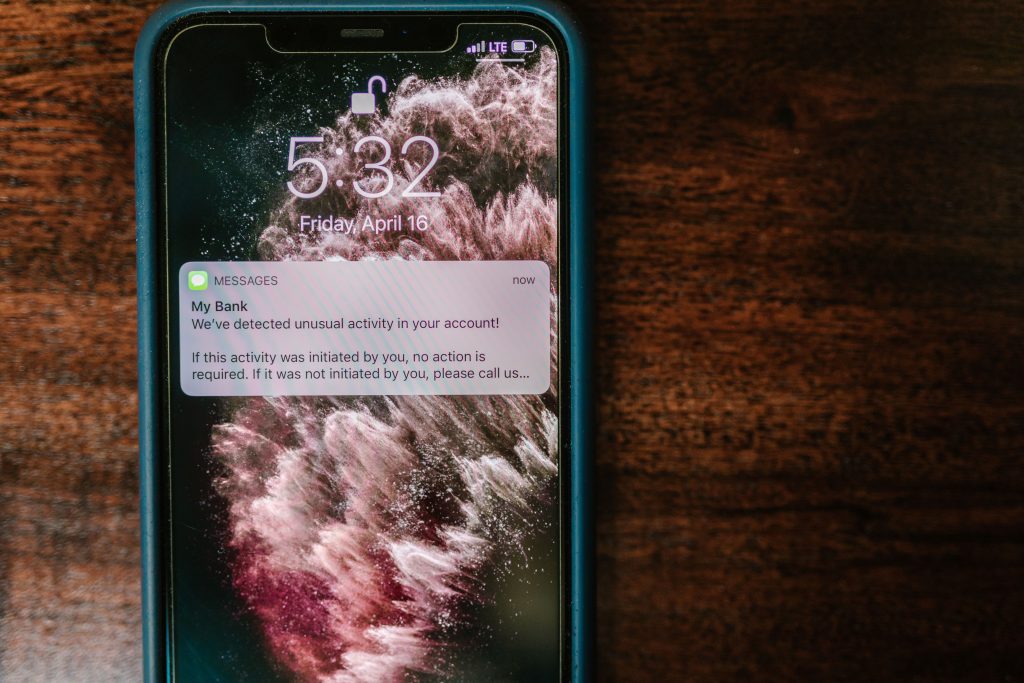
The Moment Every Borrower Worries About Before They Even Apply
Ask anyone who’s considered a crypto-backed loan what stops them, and the answer is rarely the interest rate or the paperwork. It’s the fear of the phone call nobody wants: the market drops, the collateral loses value, and something happens to the crypto without warning. That fear isn’t irrational — it’s exactly how liquidation works on plenty of leveraged trading platforms, where a falling price can trigger an automatic, forced sale with no notice at all.
LoanCryptoBank’s homepage addresses this directly, under a feature it calls “Margin call transparency”: “If the market moves against your collateral, you’re notified with a margin call before any action is taken.” That’s a specific claim, not a vague reassurance, and it’s worth taking apart piece by piece — what “notified” means, what “before any action” actually rules out, and what the FAQ says happens next.
What “Notified Before Any Action Is Taken” Actually Promises
The core structure here is sequencing. A margin call, by definition, is a warning that collateral value has moved against the loan — not the liquidation itself. What the platform is committing to is that the warning comes first, as a distinct, separate event from any sale or seizure of the collateral. That matters because the alternative — a platform that liquidates first and informs the borrower after — removes any chance to react, refinance, or add funds before losing the position entirely.
This sits alongside a second stated principle from the homepage: “Collateral custody — your crypto collateral is held by the platform for the duration of your loan and returned once it’s settled.” Combined, the two claims describe a specific shape: the collateral doesn’t move, and doesn’t get touched, without the margin call happening first. The custody promise and the transparency promise are really two halves of the same idea — nothing happens to the asset silently.
The Two Outcomes the FAQ Names for a Sharp Price Drop
The homepage explains that a margin call gets triggered. The FAQ explains what happens after one, in response to the specific question “How can a sharp drop in the rate of a Cryptocurrency affect a Loan?” The answer, quoted directly: “Perhaps, the most optimal option would be a guaranteed return of funds after the sale of collateral in the open market. The possibility of refinancing also remains valid.”
Two distinct paths are named there, not one. The first — sale of collateral in the open market — is what most people picture when they hear “margin call,” and the FAQ doesn’t hide it or soften it: the FAQ describes it as returning funds to the borrower after that sale, not simply confiscating the position. The second — refinancing — is the option that doesn’t get discussed nearly as often, and it’s the one that changes the emotional shape of a margin call from “your position gets taken” to “your position gets taken, or your terms get adjusted.”
Why Refinancing Sits Next to Liquidation, Not Behind It
The FAQ’s phrasing — “the possibility of refinancing also remains valid” — places refinancing as a standing option throughout the life of the loan, not a last-resort escape hatch offered only once liquidation is already underway. That framing lines up with how this series has covered refinancing before: extending loan terms is something a borrower can request proactively, not just in a crisis.
What that means practically for a margin call specifically: a borrower facing a dropping collateral value isn’t necessarily choosing between “do nothing and lose the collateral” or “add more funds immediately.” Refinancing — adjusting the loan’s term or structure rather than closing it out — is presented as a live alternative to letting the position run to a forced sale. Whether refinancing is the right call in any specific situation depends on the borrower’s own numbers, not on anything this article can generalize.
What Stays Visible in Your Account the Whole Time
The homepage’s fourth “how it works” point is the one that ties custody and transparency together operationally: “Track everything in your account — loan status, collateral value, and exchange history are visible in your client account at any time.” A margin call, in other words, isn’t something a borrower has to take on faith or find out about only through a notification. The collateral value that would trigger one is visible continuously, in the same client office used to manage the loan itself, rather than being a number the platform alone can see.
That visibility is what makes the “notified before any action” promise checkable rather than just stated. A borrower watching collateral value trend downward in their own account has the same information the platform is using internally to decide whether a margin call applies — there’s no separate, hidden dashboard driving the decision.
What This Doesn’t Promise
None of this eliminates the underlying risk of borrowing against a volatile asset. A crypto-backed loan means the collateral’s value can still fall enough to trigger a margin call in the first place — that’s the real, named risk in this series’ coverage of the platform, not a hypothetical. Transparency changes what happens once that risk materializes; it doesn’t remove the risk itself. LoanCryptoBank’s own FAQ doesn’t publish a specific price-drop percentage or loan-to-value threshold that triggers a margin call on its public pages, and this article doesn’t invent one — the two things that are stated plainly, and are the actual subject here, are that a warning comes before action, and that a warning is followed by a choice between two named paths, not a single automatic outcome.
This article describes how LoanCryptoBank says its margin call process works, based on its own public homepage and FAQ; it isn’t financial or investment advice, and borrowing against any volatile asset carries real risk regardless of how transparent the process around it is.